
Real Deal: A Bootle Two-Bed, From Offer to Lease

This Bootle buy-to-let was an overseas investor's first UK house: a two-bedroom terrace at 38 Smollett Street, Bootle, Liverpool L20 4PT, secured for £88,000 in February 2026. It completed in August, was refurbished in under four weeks, licensed with Sefton Council in September and leased to a social housing provider in October. Not everything went to plan, and I'll say where.
I'm George Samoila, and I run Manchester Sourcing. Most of our buyers never see the house before they own it, so I think the most useful thing I can show you is one real deal, start to finish, with the numbers.
The deal at a glance
Property: 2-bed terraced house, leasehold (999 years)
Address: 38 Smollett Street, Bootle, Liverpool L20 4PT
Price: £88,000, vacant possession
Lender's valuation: £84,000 (desktop)
Refurb quoted at offer: £10,000
Extra works agreed: £2,000
Rent quoted at offer: £775 a month
Reserved: February 2026
Completed: 14 August 2026
Refurb finished: 9 September 2026
Lease issued: 16 October 2026
Why a Bootle buy-to-let?
Bootle works for our product because prices are low against rents. At the £775 a month we quoted, that's £9,300 a year, a gross yield of about 10.6% on the £88,000 price, before finance costs, purchase costs and tax. Rents in the region are still rising: the ONS put North West private rent inflation at 5.8% in the 12 months to August 2026, joint highest in England.
This wasn't the first house the investor reserved. In February the seller of their original choice changed their mind and pulled out. It's rare, but it happens. We sent replacements the same afternoon; the investor asked us which street was the better place to live, and chose Smollett Street the next day.
How long did it take to complete?
About six months, from the memorandum of sale on 25 February to completion on 14 August. That's longer than we'd like. Most of the waiting was on paperwork between solicitors, not on the house. Buying from overseas adds steps too: identity checks, a broker and a lender who never see the house.
What happened with the mortgage valuation?
The lender did a desktop valuation and came back at £84,000, £4,000 under the price. A desktop valuer hasn't seen the house, so they tend to be cautious. The lender offered £63,000, 75% of its own valuation rather than of the price, so the investor put in the difference. We offered an in-person valuation at about £1,000; the investor decided the gap wasn't worth chasing.
This is normal and worth planning for. We wrote about it in the realities of getting a mortgage on social housing: lenders value bricks and mortar, and a down-valuation means more of your own cash, not a dead deal. With the average five-year fix hitting 6% on 5 October and the Bank of England's next decision on 5 November after three of nine members voted to raise in September, speak to your broker about the rate before you reserve.
What did the refurbishment cost?
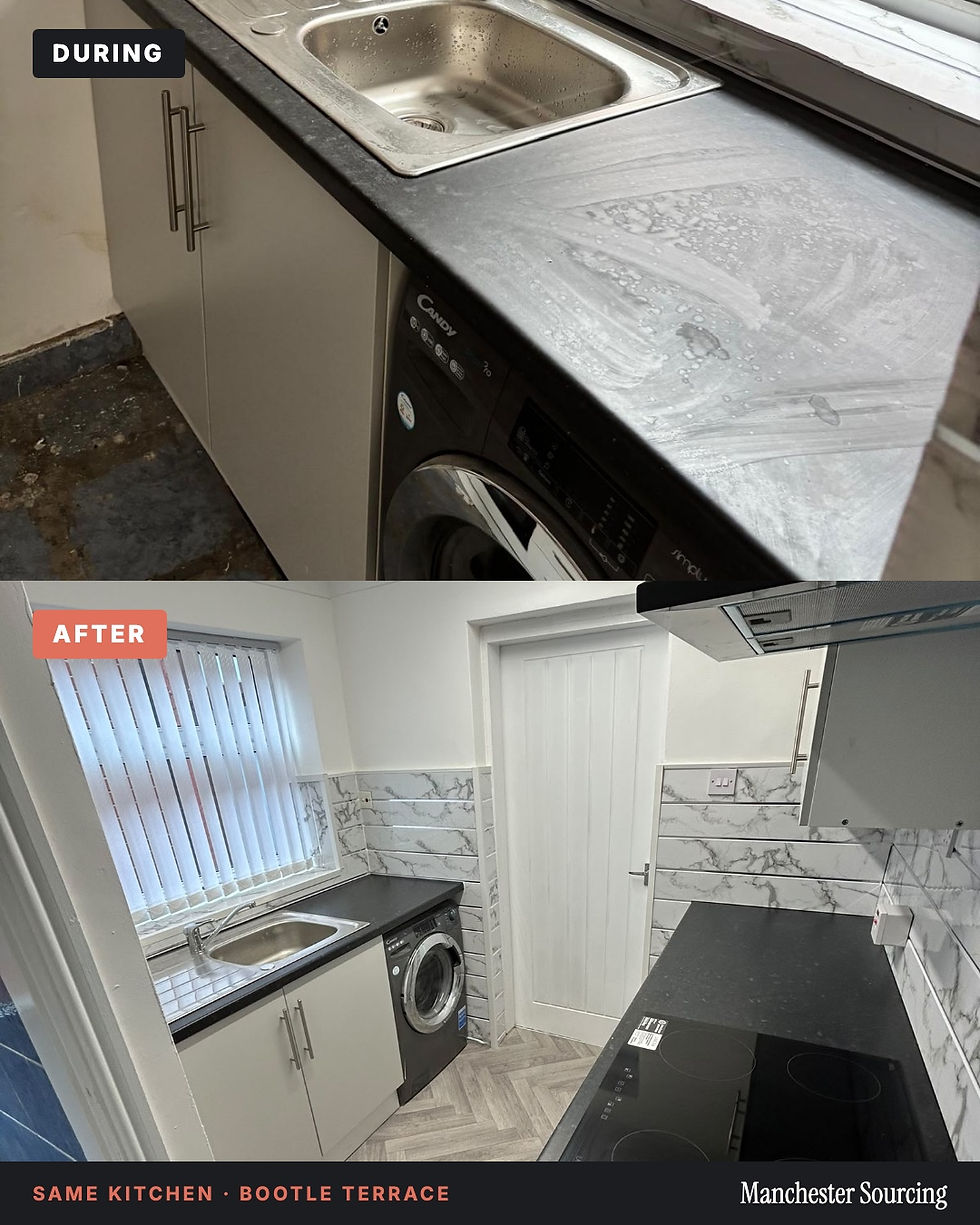
We quoted the works at offer stage, line by line:
roof: £500
flooring: £2,000
painting: £2,000
new kitchen: £3,000
bathroom repairs: £500
damp: £1,000
project management: £1,000
That's £10,000. Keys were collected on completion and a key safe fitted the same day, so the investor didn't need to be in the country. The roof was done by 3 September, carpets went in that week, and the house was finished on 9 September, under four weeks after completion.
What went wrong?

Three things, and I'd rather you hear them from me.
The bathroom was worse than it looked. Once the old fittings came out, it needed far more than £500 of repairs. We removed the electric shower and ran hot and cold to the bath taps. That came in about £3,000 over; we asked the investor for £1,500 and absorbed the rest.
The consumer unit needed replacing, another £500. Electrics are the owner's cost on a provider lease, which we explained in who pays for repairs on a social housing lease.
The lease came back shorter than we quoted. At offer stage the provider indicated a three-year contract at £775. The lease issued on 16 October is for one year. It's still rent paid by the provider rather than a tenant, but a one-year term means a renewal conversation sooner than the investor expected. We'll push for a longer term at renewal, and because we work with several providers in Liverpool and Sefton, that provider isn't the only option.
Why did it need a licence?
Bootle sits inside Sefton Council's selective licensing scheme, which has covered private rented homes in the area since 2018 and has been extended to February 2028. So before the lease, the owner had to apply online. The form wanted the full electrical report, details of the smoke alarms and the managing agent's contact. We sent everything over and the application went in on 26 September.
One more good habit from this investor: when an unfamiliar email arrived asking for information, they sent it to us and asked "is this legitimate?" before replying. Always do that.
What this means for you
A house like this is simple, but it isn't instant. Plan for:
time: months to complete, then weeks for works, licence and lease
cash: a buffer for a down-valuation and for works you can't see on a viewing
lease terms: the term is set by the provider when the lease is issued, so treat the offer-stage figure as a guide
overseas costs: currency moves, a lower loan-to-value and the non-resident stamp duty surcharge. Run your figures on our stamp duty calculator and check your own position with a tax adviser.
If you'd like to see how the steps fit together, read what it's really like to work with Manchester Sourcing, then look at our current deals.
FAQ
How long does it take to buy a buy-to-let in Bootle from overseas?
This one took about six months from memorandum of sale to completion, then around two months more for the refurbishment, licence and lease. Some complete faster. Most of the delay is paperwork between solicitors and lenders, so reply quickly to your solicitor and broker and expect it to take longer than you'd like.
What happens if the lender values the house below the price?
The lender lends against its own figure, so you put in the difference or renegotiate. Here the valuation was £4,000 under the £88,000 price, and the investor chose to proceed. An in-person valuation can sometimes close the gap, but it costs money and may not change the number.
Do I need a licence to let a house in Bootle?
Usually yes. Bootle is covered by Sefton Council's selective licensing scheme, extended to February 2028, so private rented homes there need a licence. Expect to supply an electrical report, smoke alarm details and the managing agent's contact. Check the council's own pages for the current rules before you buy.
Is the rent guaranteed for the whole lease?
The rent is paid by the provider for the term of the lease, whether or not the house is occupied. The term is set when the lease is issued, and on this house it is one year, shorter than first indicated. At the end of a term the lease is renewed, moved to another provider, or the house is let or sold.
Want to see a deal like this?
Book a 30-minute Discovery Call and I'll walk you through what's live now, the real numbers and the catches.


Comments